From Rejection Letter to Resolution: How Canadian Patients Can Fight Back Against a Denied Drug Claim
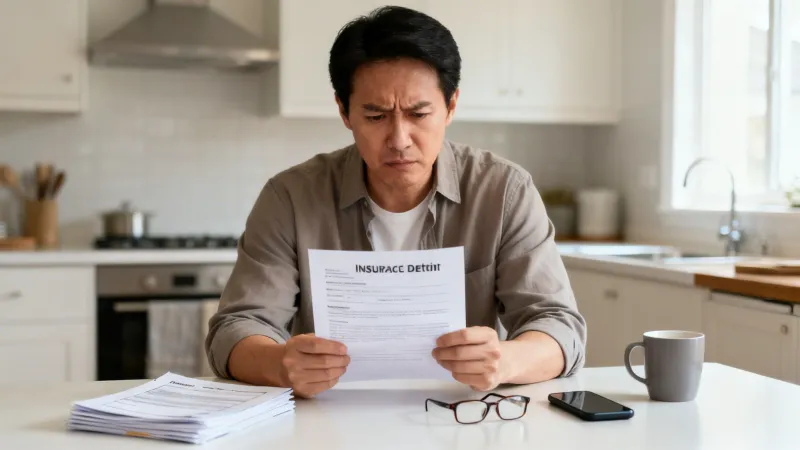
Photo: person reviewing insurance denial letter paperwork at kitchen table Canada, via cdnimg.co
The envelope arrives on an ordinary Tuesday. Inside, a letter from your private insurer explaining that the medication your doctor prescribed — the one you have been taking for months — is no longer covered, or was never approved in the first place. For many Canadian patients with employer-sponsored or private drug plans, this letter triggers panic. It should not. It should trigger a plan.
At Canadian Pharmacy Fit, we hear from patients across the country who assume a denial is final. In most cases, it is anything but. Insurers deny claims for reasons ranging from clerical errors to missing prior authorization paperwork, and a well-documented appeal reverses a surprising number of them. Here is how to work through the process methodically — and how to keep your treatment uninterrupted while you do.
Read the Denial Letter Like an Auditor, Not a Patient
Before picking up the phone, study the letter itself. Insurers are generally required to state a reason for the denial, and the specific wording matters enormously:
- Prior authorization required — the insurer needs additional clinical justification before approving the drug.
- Step therapy — the plan wants documentation that you tried (or cannot tolerate) preferred alternatives first.
- Not on formulary — the medication is excluded from your plan's approved list, though exceptions may be granted.
- Dosage or quantity limits — the plan covers the drug, but not at the prescribed amount.
- Coordination of benefits — a clerical issue when you hold more than one plan.
Each category demands a different response, and misreading the reason is the single most common reason appeals stall. Circle the exact language used. You will need it when you speak to the insurer and your pharmacist.
Your First Week: Assemble the File
Appeals are won on paperwork, and the strongest files come together in days, not weeks. Within the first week of receiving the denial:
- Call the insurer's member services line and ask two questions directly: what documentation is required to overturn this decision, and what is the deadline for a formal appeal? Record the date, time, and the representative's name.
- Request an exception or prior authorization form if the denial mentions either. Do not wait for the insurer to send one unprompted.
- Book a conversation with your pharmacist. Pharmacists see these denials daily and know precisely which forms, drug identification numbers (DINs), and clinical notes insurers expect. Many will complete the administrative portions of the paperwork for you.
- Ask your prescriber for a letter of medical necessity. A short, specific letter — your diagnosis, why alternatives are unsuitable or have failed, and the consequences of interruption — carries more weight than any patient-written appeal.
Keep copies of everything. A dedicated folder, physical or digital, turns a chaotic process into a checklist.
The Formal Appeal: What to Submit and When
Most private plans in Canada allow 30 to 90 days from the denial date to file a formal appeal, though timelines vary by insurer and by province. Submit well before the deadline, and include:
- The completed exception or prior authorization form
- The prescriber's letter of medical necessity
- Any relevant clinical notes documenting failed alternatives or adverse reactions
- The original denial letter, with the reference number clearly noted
If the insurer offers a peer-to-peer review — a conversation between your physician and the insurer's medical reviewer — accept it. These reviews resolve a meaningful share of disputes without further escalation.
If the first appeal fails, ask about a second-level or external review. In some provinces, patients with private plans can escalate to an ombudsperson or, for certain workplace plans, to the provincial insurance regulator. The path exists; few patients ever use it.
The Parallel Track: Keeping Treatment Going While You Wait
Here is the uncomfortable truth about appeals: even a strong one can take four to eight weeks. Patients rarely have that kind of time with a chronic condition. This is where the pragmatic question shifts from how do I win the appeal to how do I stay treated in the meantime.
Two strategies deserve consideration, and they are not mutually exclusive:
The 90-day fill. If your plan covers the medication at a standard quantity but you are staring down a coverage gap, a 90-day supply — purchased at cash price or through a discount arrangement — can bridge the appeal period at a lower per-unit cost than three separate 30-day fills. Ask your pharmacist to price out all three scenarios before you decide.
The cross-border comparison. For certain brand-name medications, the Canadian and cross-border price difference is substantial enough that paying out of pocket abroad, or through a licensed Canadian source, costs less than a full appeal cycle of cash pricing at home. This route requires care — a valid prescription, a licensed pharmacy, and awareness of what can legally be personally imported — but for patients rationing doses to stretch a supply, it is often the safer and cheaper option. We have covered the legal framework in detail in our cross-border guides.
The key is to run both tracks simultaneously. File the appeal to protect your long-term coverage, and use a bridge strategy to protect your health in the short term.
When the Appeal Succeeds — and When It Should Teach You Something
A successful appeal restores coverage, often retroactively. Submit your receipts for any bridge-period purchases and ask about reimbursement; some plans will honour them retroactively once the denial is overturned.
But even a loss carries information. If your plan denies a drug permanently, ask your pharmacist to identify therapeutic alternatives on formulary, and ask your prescriber whether any are clinically equivalent for your situation. And if you find yourself appealing the same class of medication repeatedly, it may be time to review your plan during your employer's next enrolment window — formularies vary more widely than most employees realize.
A denial letter is a bureaucratic event, not a medical verdict. Treated with the same rigour you would bring to any other negotiation — documentation, deadlines, and a parallel plan — it is a problem with a known solution. The patients who win are rarely the ones with the loudest complaints. They are the ones with the neatest folders.